Author: Bryson Reid

  • Hook ’Em & Home Sweet Home!

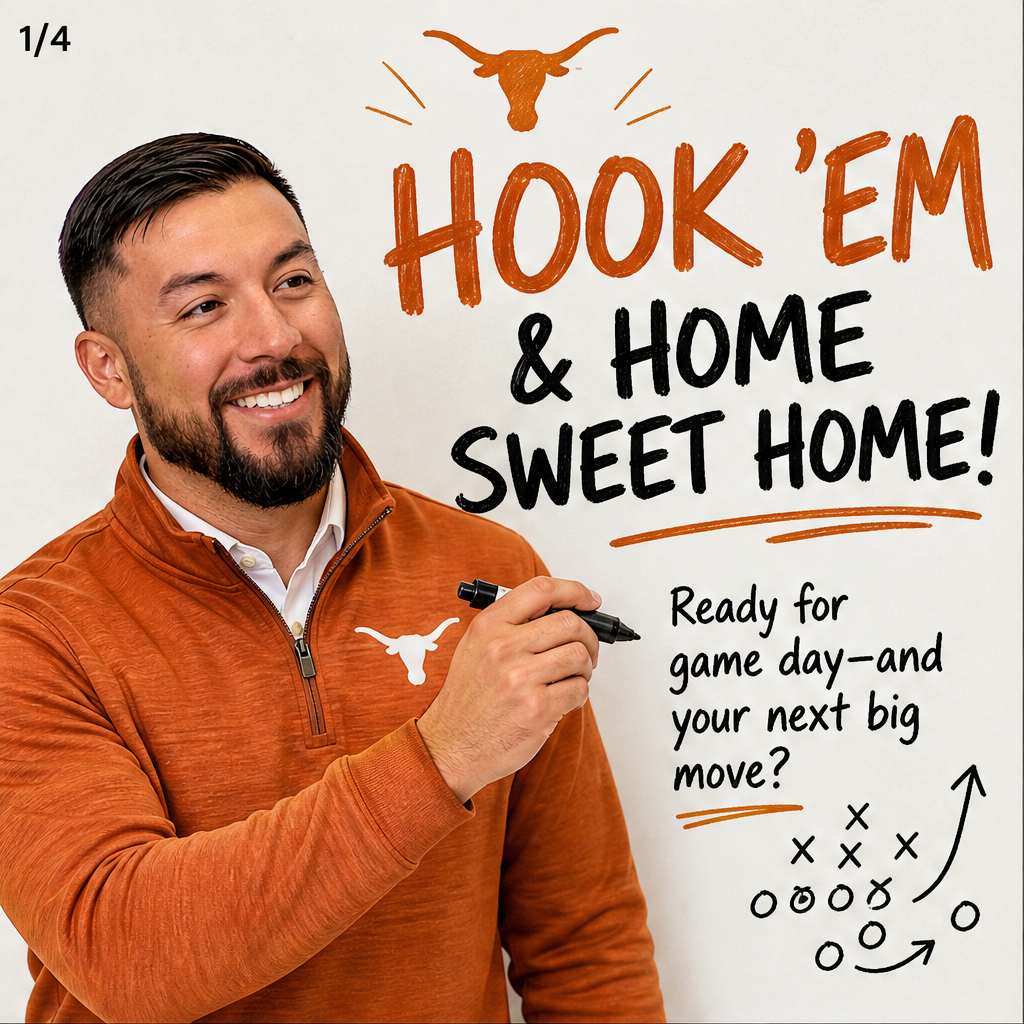
    Hook ’Em & Home Sweet Home!

    No. 1 Texas takes on the UTSA Roadrunners Saturday, September 19, 2026, at 7:00 PM CT inside Darrell K Royal–Texas Memorial Stadium in Austin. As proud Longhorns fans, we’re bringing the burnt orange energy to every slide while connecting game-day preparation with the homebuying journey. From building a smart mortgage strategy to finding your ideal home across Austin and Central Texas, preparation helps you step confidently into your next opportunity. Cheer loud, dream big, and when you’re ready to make your move, let our mortgage team help create your personalized game plan. Hook ’Em!

    Continue to full article

  • Hook ’Em & Home Sweet Home!

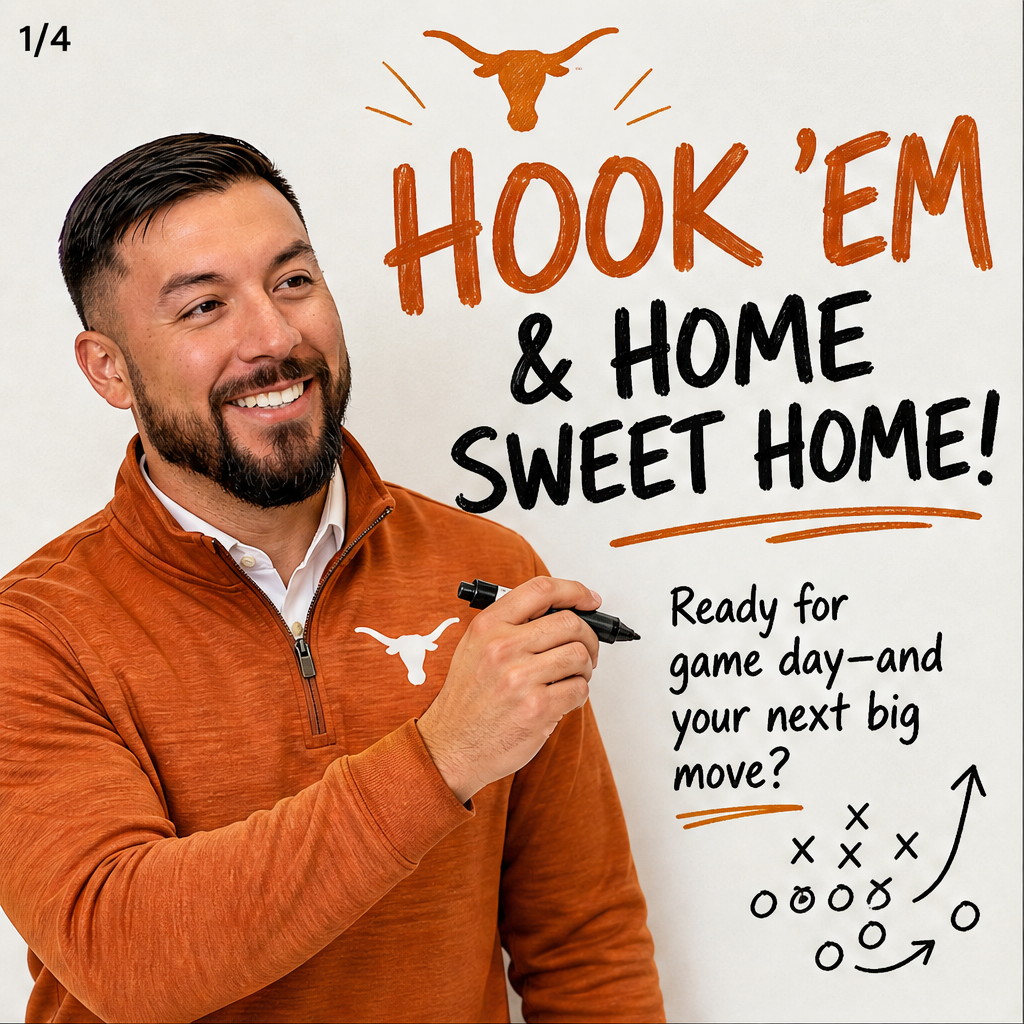
    Hook ’Em & Home Sweet Home!

    No. 1 Texas takes on the UTSA Roadrunners Saturday, September 19, 2026, at 7:00 PM CT inside Darrell K Royal–Texas Memorial Stadium in Austin. As proud Longhorns fans, we’re bringing the burnt orange energy to every slide while connecting game-day preparation with the homebuying journey. From building a smart mortgage strategy to finding your ideal home across Austin and Central Texas, preparation helps you step confidently into your next opportunity. Cheer loud, dream big, and when you’re ready to make your move, let our mortgage team help create your personalized game plan. Hook ’Em!

    Continue to full article

  • Travis County Market Update

    Here’s a quick update on the Travis County real estate market. Homes are taking a similar amount of time to sell as before. The number of homes available and those being purchased remain consistent.

  • Fixed vs. Variable: Which Mortgage Fits Your Financial Future?

    Fixed vs. Variable: Which Mortgage Fits Your Financial Future?

    Choosing between a fixed and variable mortgage depends on more than today’s interest rate. A fixed-rate loan offers payment stability and predictable budgeting, which may suit buyers with steady income or low risk tolerance. A variable-rate mortgage may provide an attractive starting rate and flexibility for buyers who expect to move, refinance, or manage changing rates comfortably. Austin borrowers should evaluate their income, savings, future plans, and ability to handle payment changes. Comparing both options with a qualified mortgage broker can help you make a confident decision aligned with your financial situation.

    Continue to full article

  • Start With a Plan, Not a Listing

    Before you start scrolling through listings, I always encourage clients to put a plan in place first. Knowing your real numbers—your income, debts, regular bills, and what monthly payment truly feels comfortable—can make the difference between enjoying homeownership or feeling stretched each month. I've seen too many people underestimate the value of a clear budget, especially at the start.

    Checking your credit early is another smart move. Even a few small corrections or paying down balances can make a real difference in the loan offers you’ll receive, and those small improvements can translate to meaningful savings over the years.

    It's also important to save beyond just the down payment. Factoring in closing costs, moving expenses, and those inevitable first repairs helps prevent unwelcome surprises from knocking you off track in those crucial early months as a new homeowner.

    Getting pre-approved before you start touring homes not only sharpens your search but signals to sellers that you’re a serious contender—often strengthening your position in a competitive market.

    And finally, having a buyer’s agent who understands your local market, can spot red flags, and advocate clearly on your behalf makes all the difference. When you’ve got the right plan and the right team, the closing table feels a lot less intimidating. My approach is all about making sure you’re informed, comfortable, and prepared at every stage.
  • US Mortgage Payoff Strategy Matters Now

    Over the past five years, about one in four US mortgage borrowers have chosen to make extra payments toward their principal—proof that accelerating your mortgage payoff is on many people’s minds. As someone who’s spent years guiding clients through the ins and outs of home financing, I know how important it is to weigh your options carefully. Experts point out that if you’re sitting on a low-rate mortgage, making extra payments might not be as impactful, especially when higher-interest debts like credit cards are still on your plate. However, for roughly one in five borrowers with mortgage rates above 6%, paying extra principal can make a real difference to your long-term costs.

    There are a few ways to approach a faster payoff: adding a bit more to your monthly payment, making a lump-sum recast to lower your monthly bill, or refinancing into a shorter-term loan. Right now, with 30-year fixed rates hovering near 7%, refinancing isn’t as appealing as it once was. In many cases, the simplest move is just to pay a little more each month. My role is to help you see how these choices fit your overall financial picture, so you can make decisions with confidence and clarity.

  • Earnest Money Isn’t Lost Money 💰

    Earnest Money Isn’t Lost Money 💰

    Think of it as a deposit: Earnest money shows the seller you’re serious and is typically held in escrow after contract acceptance.
    It can become your credit: At closing, your earnest money is generally applied toward your down payment, closing costs, or other approved expenses.
    Protect your deposit: Follow the contract deadlines and ask your Austin mortgage broker how earnest money will appear on your final Closing Disclosure.
    Buying in Austin? Let’s review your numbers and make sure your earnest money is properly documented and credited at closing. Send us a message to get started!

    Continue to full article

  • Mortgage Approval Documents

    One of the first questions I get from clients—whether they’re first-time buyers or seasoned investors—is what documents will be needed for mortgage approval. Having helped people through this process since 2015, I know that paperwork can feel overwhelming, but a little preparation goes a long way. Lenders look closely at your finances to make sure the loan is affordable for you, so expect to provide documentation for income, employment, savings, and details of any current debts. Typically, you’ll need proof like recent pay stubs, W-2s, or records for bonuses and rental income, plus your current employer’s info and a two-year work history. If you’re self-employed, tax returns or transcripts become especially important. Identification such as a government-issued ID and Social Security number are standard, and you might be asked for your address history and recent bank or investment statements to verify down payment and reserves. Lenders also use your credit history and monthly obligations—think car loans or child support—to calculate your debt-to-income ratio. And if you’re using gift funds for your down payment, a gift letter and transfer records will be needed. In my experience, pulling these documents together early can ease the process and help you move forward with confidence.

  • Why Texas Homeowners Are Treating Home Equity as a Financial Planning Tool, Not Just a Loan

    Why Texas Homeowners Are Treating Home Equity as a Financial Planning Tool, Not Just a Loan

    Home equity isn’t just a loan—it’s a financial strategy that more Texas homeowners are using to their advantage. If you own your primary residence in Texas, you can access up to 80% of its value through a home equity loan, and enjoy the predictability of fixed rates. Whether you’re considering renovations, consolidating debt, or funding education, these funds can offer real flexibility—while the 12-day cooling-off period gives you time to consider your options with confidence. For many of my clients, understanding how to use home equity is a key part of creating a stronger financial foundation. My approach has always been to break down these choices in plain English, empowering you to make informed decisions about your home and your future.

    Continue to full article

  • When to Refinance Your Mortgage: A Guide to Lowering Payments

    When to Refinance Your Mortgage: A Guide to Lowering Payments

    Refinancing your mortgage can be a smart move—if you know what to look for and how the process works. Since 2015, I’ve helped clients from all walks of life break down the refinancing process into practical steps. Essentially, refinancing means replacing your current mortgage with a new one, often to secure a lower rate, reduce your monthly payments, or even shorten your loan term. But timing and personal circumstances matter: it’s important to weigh current interest rates, your home equity, and ensure your credit score is typically at least 620. Don’t forget to factor in the costs involved and consider how long you plan to stay in your home before starting the process. My goal has always been to make these decisions less overwhelming and to equip you with the knowledge you need, whether you’re a first-time homeowner or a seasoned investor. Empowering clients to navigate these choices with clarity is what I love most about this work.

    Continue to full article